Highlights
- Rolls-Royce shares have climbed 27% in the past year, sparking investor interest.
- Morgan Stanley maintains a target price of 2,000p despite recent price declines.
- Market analysts project an average price target of 1,747p for the coming year.
- Concerns about valuation and external factors affecting the aerospace sector persist.
- Investing expert Mark Rogers highlights more attractive market opportunities.
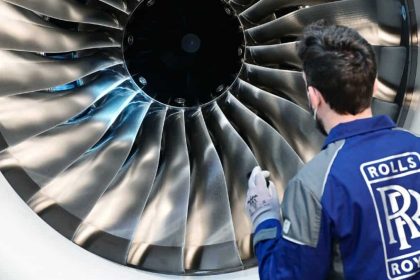
Rolls-Royce Holdings Plc has emerged as a hot topic among retail and institutional investors, particularly following a robust year in which its shares rose by 27%. Yet, as enthusiasm builds, analysts remain divided on whether the current price reflects a sound investment, especially after the stock recently slipped by 7%. This ever-shifting landscape invites scrutiny and analysis, particularly as various research teams, including that of Morgan Stanley, weigh in on the stock’s future.
Morgan Stanley recently reiterated its target price for Rolls-Royce at 2,000p, up from an earlier forecast of 1,500p. This optimistic stance is noteworthy, particularly given the stock’s recent downturn. The current trading price of 1,419p indicates that reaching 2,000p within the year would represent a significant 41% increase. While one should appreciate the confidence exhibited by Morgan Stanley, it’s essential to consider broader analyst sentiment, which averages a target price of 1,747p—still optimistic but more measured than the bank’s forecast.
From a valuation perspective, Morgan Stanley’s 2,000p target might appear aggressive. The projected price would equate to around 45 times the current consensus forecast for 2027 earnings. Even if one looks ahead to 2028 estimates, the valuation remains a hefty 38 times earnings. This raises questions about the sustainability of such high expectations for a company operating in the aerospace and defence sectors, which are subject to various economic pressures.
Oil prices hovering above $100 a barrel exert upward pressure on fuel costs, posing risks for the airline industry—an area crucial to Rolls-Royce’s Civil Aerospace division. Any adverse developments, particularly as we approach peak winter travel, could pose challenges for the company, compounded by existing supply chain concerns that are not yet resolved.
Long-term prospects look more promising. Sectors such as defence spending, data centres, and small modular reactors (SMR) present opportunities that could drive earnings growth. However, at present valuations, the good news that investors are banking on appears almost necessary rather than surprising. For Rolls-Royce to achieve a target of 2,000p, it would likely need to consistently surpass already high expectations.
Despite the company’s solid financial performance, which saw a 46% increase in underlying operating profit to £2.5 billion in the first half of the year, cautious investors might find more value in less inflated stocks. Mark Rogers, an investing expert, suggests that now might not be the best time for an investment of £5,000 in Rolls-Royce without exploring his opportune suggestions covering other potentially undervalued stocks in the market.
As the aerospace and defence sectors continue to navigate a complex financial landscape, investors would do well to remain informed and discerning. The pressure to meet lofty expectations could prove to be a significant hurdle for Rolls-Royce. Interestingly, the global aerospace market is projected to grow at a CAGR of 4.4% from 2023 to 2033, which may benefit companies like Rolls-Royce in the long run, but investors must weigh this against current market volatility and valuation concerns.
For further insights into Rolls-Royce’s performance and analysis, check out the detailed discussion by Jon Smith on Twelfth Magpie.
Related Posts
- North Cork Company Alps Enhances MedTech Expertise with New ISO Certification
- LVMH Drops from Europe’s Top 10 Market Leaders!
- OpenAI Taps Cork Native Mark Bambury to Head EMEA Advertising Business
- Klearcom Strengthens Leadership with Two Key Appointments Amid Global Expansion Efforts
- Reddit Stock Drops 4% Despite Robust User Growth and Revenue Performance